Investment Philosophy
OUR PRODUCTS OFFERINGS
BOTTOM UP APPROACH
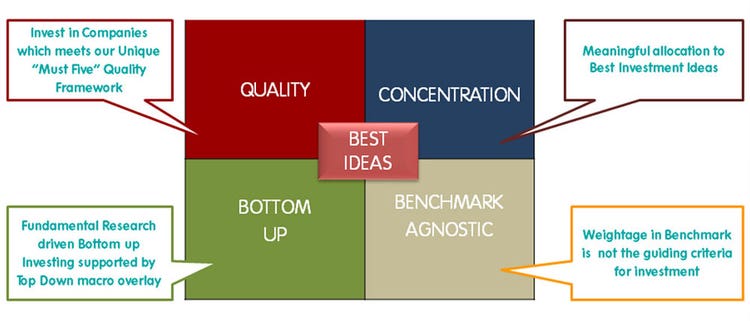
We believe that in all market conditions and across all capitalizations, there are stocks which may outperform. Hence, our Focus is on identifying such stocks, within the chosen sectors. Sectoral trends and macroeconomic research is used to identity macro trends / sectoral opportunities. Our Conviction in our stock picks come from rigorous bottom up fundamental research. Fundamental Research involves study of historic track record, trends and future earning estimates through the lens of “Must 5” Quality framework.
The Assessment is based on Earnings Growth, Operating Leverage, Demand Environment, Margin Expansion, and Financial Leverage. Assessment also includes Senior Management Interaction, Key Customer, Suppliers feedback, Competition feedback, Key Stakeholders Interaction.
Post identification of stocks based on rigorous fundamental research, we identify reasonably priced stocks, based on Valuation gap analysis
- Historical Vs Current valuations
- Peer Group Valuation
- Potential Rerating Triggers
Investment is made in stocks with the Highest Conviction. Such companies tend to weather sector declines. Our endeavour is to benefit from the early identification of an investment idea; where there is higher potential for outsize returns
MUST 5 FRAMEWORK
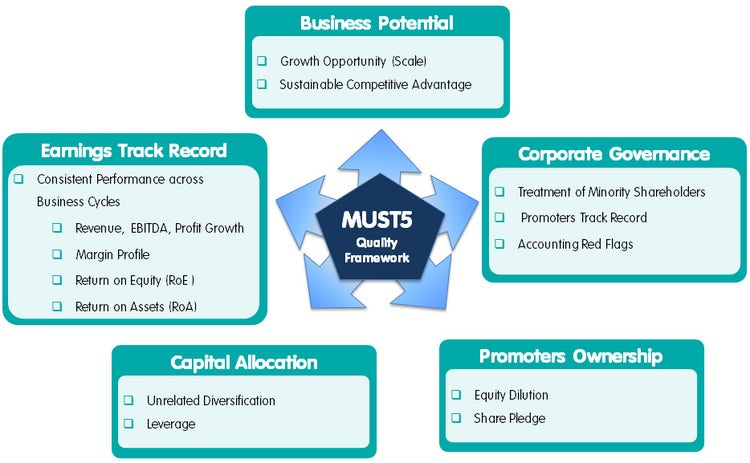
We follow a 2 step investment process which first starts with top down approach to identify sectors we like and follow that with bottom up approach to identify stocks within those sectors. Based on local & global macro-economic inputs, sector valuation and outlook we identify the sectors we would like to invest in. Once we have eliminated the sectors we want to avoid and identified our universe, we do Bottom Up stock level analysis to cherry pick individual stocks. Bottom up stock analysis and selection from the shortlisted universe is based on our “Must 5” Framework:
WHY BENCHMARK AGNOSTIC?
Our aim is to invest in stocks and sectors, which have potential to give relatively outsize returns over next 3-5 years, irrespective of their weights in the benchmark. There is no compulsion to buy the high weightage stocks / sector if the Portfolio Manager does not have high conviction on them or if Portfolio Manager doesn’t see the value in those stocks compared to other peer group companies. Therefore, this results in a portfolio of best ideas, which is “unfettered” from the benchmark
WHY CONCENTRATION
Concentration builds meaningful allocation in our Best Investment Ideas. Typically, it is seen that there is no significant reduction in Portfolio Risk (SD) beyond 20-25 stocks. We believe over diversification leads to Average Returns and hence, Our Concentrated Portfolios aim to avoid excessive diversification.